Supreme Court Upheld Repudiation of Fire Insurance Claim
Judgment dated 21.9.2026 of the Supreme Court of India in Civil Appeal No.7221 of 2025 of M/s New India Assurance Company Ltd Vs. M/s Hemkund Duplex and Board Pvt Ltd. With connected civil appeal.
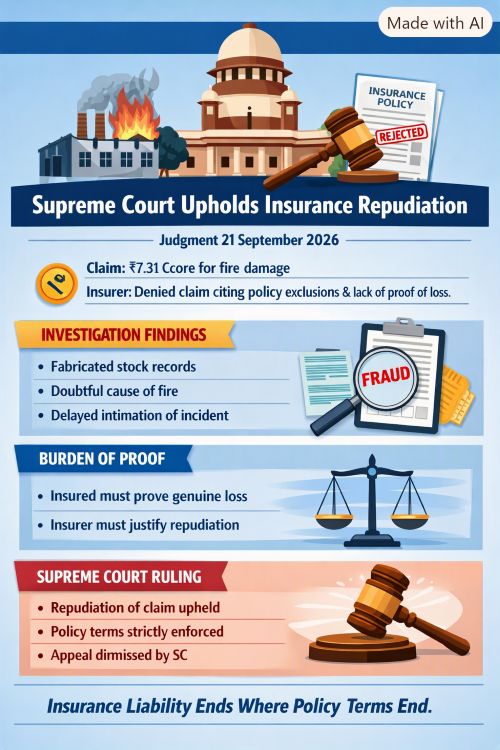
The claim put forth by the respondent, M/s. Hemkund Duplex and Board Pvt. Ltd., the complainant in Consumer Complaint No. 66 of 2011, was for compensation of ₹7,31,31,096.78, with interest @18% per annum, apart from other damages, on the strength of two fire insurance policies that it had with the appellant insurance company.
The fire policy for the stock was for a sum of ₹13,00,00,000/- and the coverage was from 30.12.2008 to 29.12.2009. The fire policy for the buildings, plant and machinery was for a sum of ₹14,00,00,000/- and the coverage was from 28.02.2009 to 27.02.2010.
On 7.5.2009, there was fire in the factory. On 8..2009, the Insurer appointed preliminary surveyor. On 9.5.2009, the insured filed insurance claim.
In the report dated 24.6.2009, the Surveyor opened that the case required meticulous investigation to rule out the possibility of a deliberate fire and hypothetical loss. Having said so, he tentatively assessed the net loss of the stock and building at ₹56,46,681/-
The appellant then appointed detective and investigative agency. In its report dated 2.3.2010, it was said that the date and time of the fire seemed genuine but the cause of the fire was not clear. the tin shed was in an isolated place inside the factory and workers rarely visited it; there was no chance of anybody throwing an ignited beedi/ cigarette in the godown, as smoking was prohibited inside the factory; even throwing of ignited material from outside the factory was remote, as it was covered with a roof and there was a boundary wall of sufficient 3 height around the factory; and there seemed to be no usable stock inside the tin shed. The fire station was informed one hour after the fire though it was just 06-07 kms away from the factory but the respondent did not bother to send someone.
The final Surveyor in the report dated 13.3.2010 said that the accurate cause of the 5 fire remained unestablished and no evidence had been adduced to hold that this was an accidental fire.
On 28.6.2010, the claim was repudiated on the ground that the accounts were manipulated to inflate th claim, the tin shed had been broken down before the fire; the chance of the fire due to a short circuit was nil; the fire station was informed about one hour late, though it was just 6 kilometers away from the factory; and the cause of the fire was doubtful.
Section 64UM(1-A) of the Act of 1938 states that every surveyor and loss assessor shall comply with the code of conduct in respect of their duties, responsibilities and other professional requirements as may be specified by the regulations made by the Authority.
The scheme of Section 64-UM(2), (3) and (4) showed that an insurer could not appoint a second surveyor as a matter of course. It was observed that the insurer must specify cogent reasons, without which it would not be free to appoint a second surveyor so as to get a report which would satisfy its interest. 23. However, in the present case, R.C. Bajpai, the first surveyor, had recorded that the abnormalities of the case needed to be investigated meticulously to rule out the possibility of a deliberate fire and hypothetical loss. His tentative assessment of the loss was subject to that finding. He had, therefore, advocated for further investigation in clear terms.
Pertinently, we find that the respondent acknowledged receipt of the reports of the two surveyors and the investigating agency in its Consumer Complaint No. 66 of 2011 but, except for baldly stating that the surveyors and the investigator gave negative reports and asserting its innocence in the context of the maintenance of the stock taking and books of accounts, the respondent did not point out any specific deficiency on the part of the surveyors, in terms of the statutory requirement.