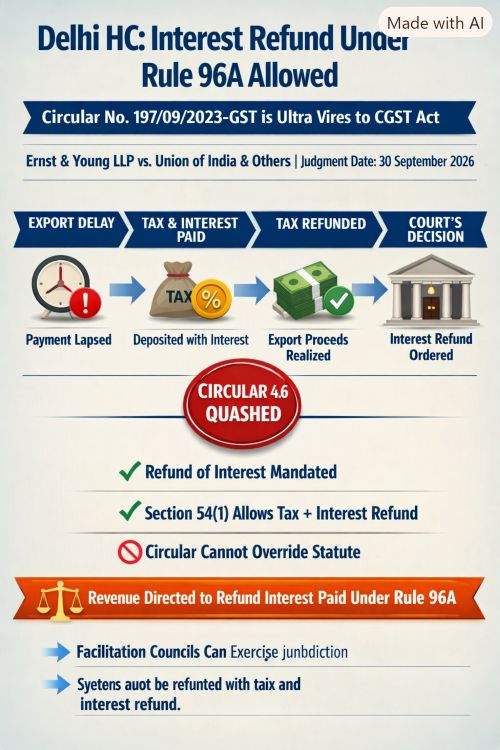
Refund of Interest under Rule 96A CGST Rules Allowed – Para 4.6 of 17.7.2023 Circular Bad In Law
Judgment dated 30.9.2026 of the High Court of Delhi in CWP No.19850 of 2024 of Ernst and Young LLP Vs. Union of India and others
This writ petition has been filed by the petitioner, Ernst and young LLP, seeking quashing of the order dated 28.02.2023 passed by the Appellate Authority, i.e., Additional Commissioner (Appeals), Gurugram, to the extent that it rejects the petitioner’s claim for refund of interest paid under Rule 96A of the Central Goods and Services Tax Rules, 2017 (“the Rules”). The petitioner has further sought a declaration that Paragraph 4.6 of the Circular No.197/09/2023 GST dated 17.07.2023 is ultra vires the provisions of the Central Goods and Services Tax Act, 2017 (“the CGST Act”), to the extent that it provides that a supplier is not entitled to seek refund of interest paid under Rule 96A of the Rules.
The petitioner is engaged in the export of professional services to clients located outside India. In respect of the exports in question, the petitioner did not pay Integrated Goods and Services Tax (IGST) at the time of supply, having furnished a Letter of Undertaking (LUT) under Rule 96A of the Central Goods and Services Tax Rules, 2017 (for short, “the CGST Rules”). The said Rule permits an exporter to export goods or services without upfront payment of tax, subject to fulfilment of the conditions prescribed thereunder. Rule 96A(1)(b) of the CGST Rules, as applicable to the case of the petitioner, required the payment for export of services to be realised in convertible foreign exchange within a period of one year from the date of the invoice. In the event of failure to realise such payment within the stipulated period, the exporter was required to pay the tax which would otherwise have been payable on such export, along with interest under Section 50 of the Central Goods and Services Tax Act, 2017 (for short, “the CGST Act”) for the period of delay. 3. In the present case, the petitioner could not realise the export consideration within the stipulated period of one year and, accordingly, deposited the tax along with interest in terms of Rule 96A of the CGST 2024 Rules. It is not in dispute that the export consideration was subsequently realised by the petitioner, though after expiry of the aforesaid period.
The short question that, therefore, arises for consideration is whether, once the tax deposited by the petitioner under Rule 96A of the CGST Rules has been refunded upon subsequent realisation of the export proceeds, the interest paid along with such tax can still be retained by the Revenue solely on the strength of paragraph 4.6 of Circular No. 197/09/2023-GST dated 17.07.2023, which provides that no refund of the interest paid in compliance with Rule 96A(1) shall be admissible.
Rule 96A(1) (b) requires an exporter of services, who has exported without payment of tax under an LUT, to realise the export proceeds within the prescribed períod. On failure to do so, the tax becomes payable along with interest under Section 50. The Rule, however, does not provide for the consequence where the export proceeds are subsequently realised and the tax so deposited is refunded. More particularly, it does not provide that the interest paid along with such tax shall nevertheless be retained. The restriction against refund of interest is found in paragraph 4.6 of the Circular.
In view of the above, we are of the considered opinion that paragraph 4.6 of Circular No. 197/09/2023-GST dated 17.07.2023, insofar as it provides that no refund of interest paid under Rule 96A(1) shall be admissible even where the tax deposited under the said Rule is subsequently refunded, cannot be sustained. Neither Rule 96A nor the provisions of the Act provide for retention of such interest in these circumstances, whereas Section 54(1) expressly contemplates a claim for refund of tax and interest paid thereon. A circular cannot impose a restriction which does not find place in the Act or the Rules. To that extent, paragraph 4.6 of the Circular must yield to the statutory provisions.
Paragraph 4.6 of Circular No. 197/09/2023-GST, dated 17.07.2023 is declared bad in law and is hereby quashed, to the extent that it provides that no refund of interest paid in compliance of Sub-Rule (1) of Rule 96A of the Rules shall be admissible where the tax paid along with such interest has subsequently been refunded upon realization of the export proceeds.